What if you discovered that the insurance policy protecting your property’s walls does absolutely nothing to protect the rent hitting your bank account? It’s a sobering realization for many investors who find themselves caught in the middle of the rental guarantee vs property insurance UAE debate only after a tenant stops paying. While one safeguards the bricks and mortar, the other ensures your monthly income remains uninterrupted regardless of tenant behavior.
We understand the stress of chasing unreliable payments and the sudden sting of emergency repair costs. It’s exhausting to manage a portfolio when you’re constantly looking over your shoulder for the next bounced cheque or a legal hurdle that could drain your returns. You’ve worked hard to build your wealth, and you shouldn’t have to act as a debt collector just to see a profit from your investment.
This guide provides a clear framework for distinguishing between physical asset protection and rental income security. You’ll discover how to automate your rent collection through digital Direct Debits and leverage modern shields that cover everything from tenant non-payment to urgent maintenance. By the end, you’ll know exactly how to secure your UAE property investment for total, long-term peace of mind.
Key Takeaways
- Distinguish between safeguarding your property’s physical structure and securing your actual monthly income to ensure consistent liquidity.
- Transition from the stress of bounced cheques to a modernized system using digital Direct Debit for seamless, automated rent collection.
- Navigate the rental guarantee vs property insurance UAE landscape to understand how each service addresses different risks like tenant default or structural damage.
- Learn how integrated emergency maintenance services within a rental guarantee can prevent minor repairs from becoming major financial drains.
- Create a comprehensive protection strategy that combines traditional insurance with tech-forward guarantees to bulletproof your investment portfolio.
Understanding Income Risk in the UAE Rental Market (2026)
The UAE rental market is experiencing a significant transformation. With over 200,000 tenancy contracts registered in the first half of 2026 alone, the volume of transactions is reaching new heights. However, this rapid growth brings fresh complexities. Traditional security measures, once considered the gold standard, are proving insufficient against modern financial risks. Many investors mistakenly believe that building insurance provides a safety net for every scenario. In reality, there’s a stark divide in the rental guarantee vs property insurance UAE discussion: one protects the structure, while the other protects your cash flow.
Physical asset safety doesn’t equate to financial liquidity. Market volatility can impact rental yields overnight. If a tenant defaults, your yield evaporates, yet your mortgage and service charges remain due. This creates a dangerous gap. Landlords are now moving toward proactive risk management models that treat rent as a guaranteed financial product rather than a variable outcome. You shouldn’t have to wait for a crisis to realize your income isn’t as secure as you thought.
The Evolution from Post-Dated Cheques to Digital Payments
The reliance on post-dated cheques is declining. In a modern economy, these paper promises are prone to failure and administrative friction. Digital payments, specifically Direct Debit, are becoming the preferred standard across the UAE. Regulatory shifts now favor these automated systems because they reduce payment failure at the source. This transition isn’t just about convenience; it’s about shifting the global concept of rent insurance into a localized, digital-first reality. By moving away from cheques, you eliminate the “bounced payment” stress that has plagued the market for decades.
Why Traditional Methods Fail to Protect Cash Flow
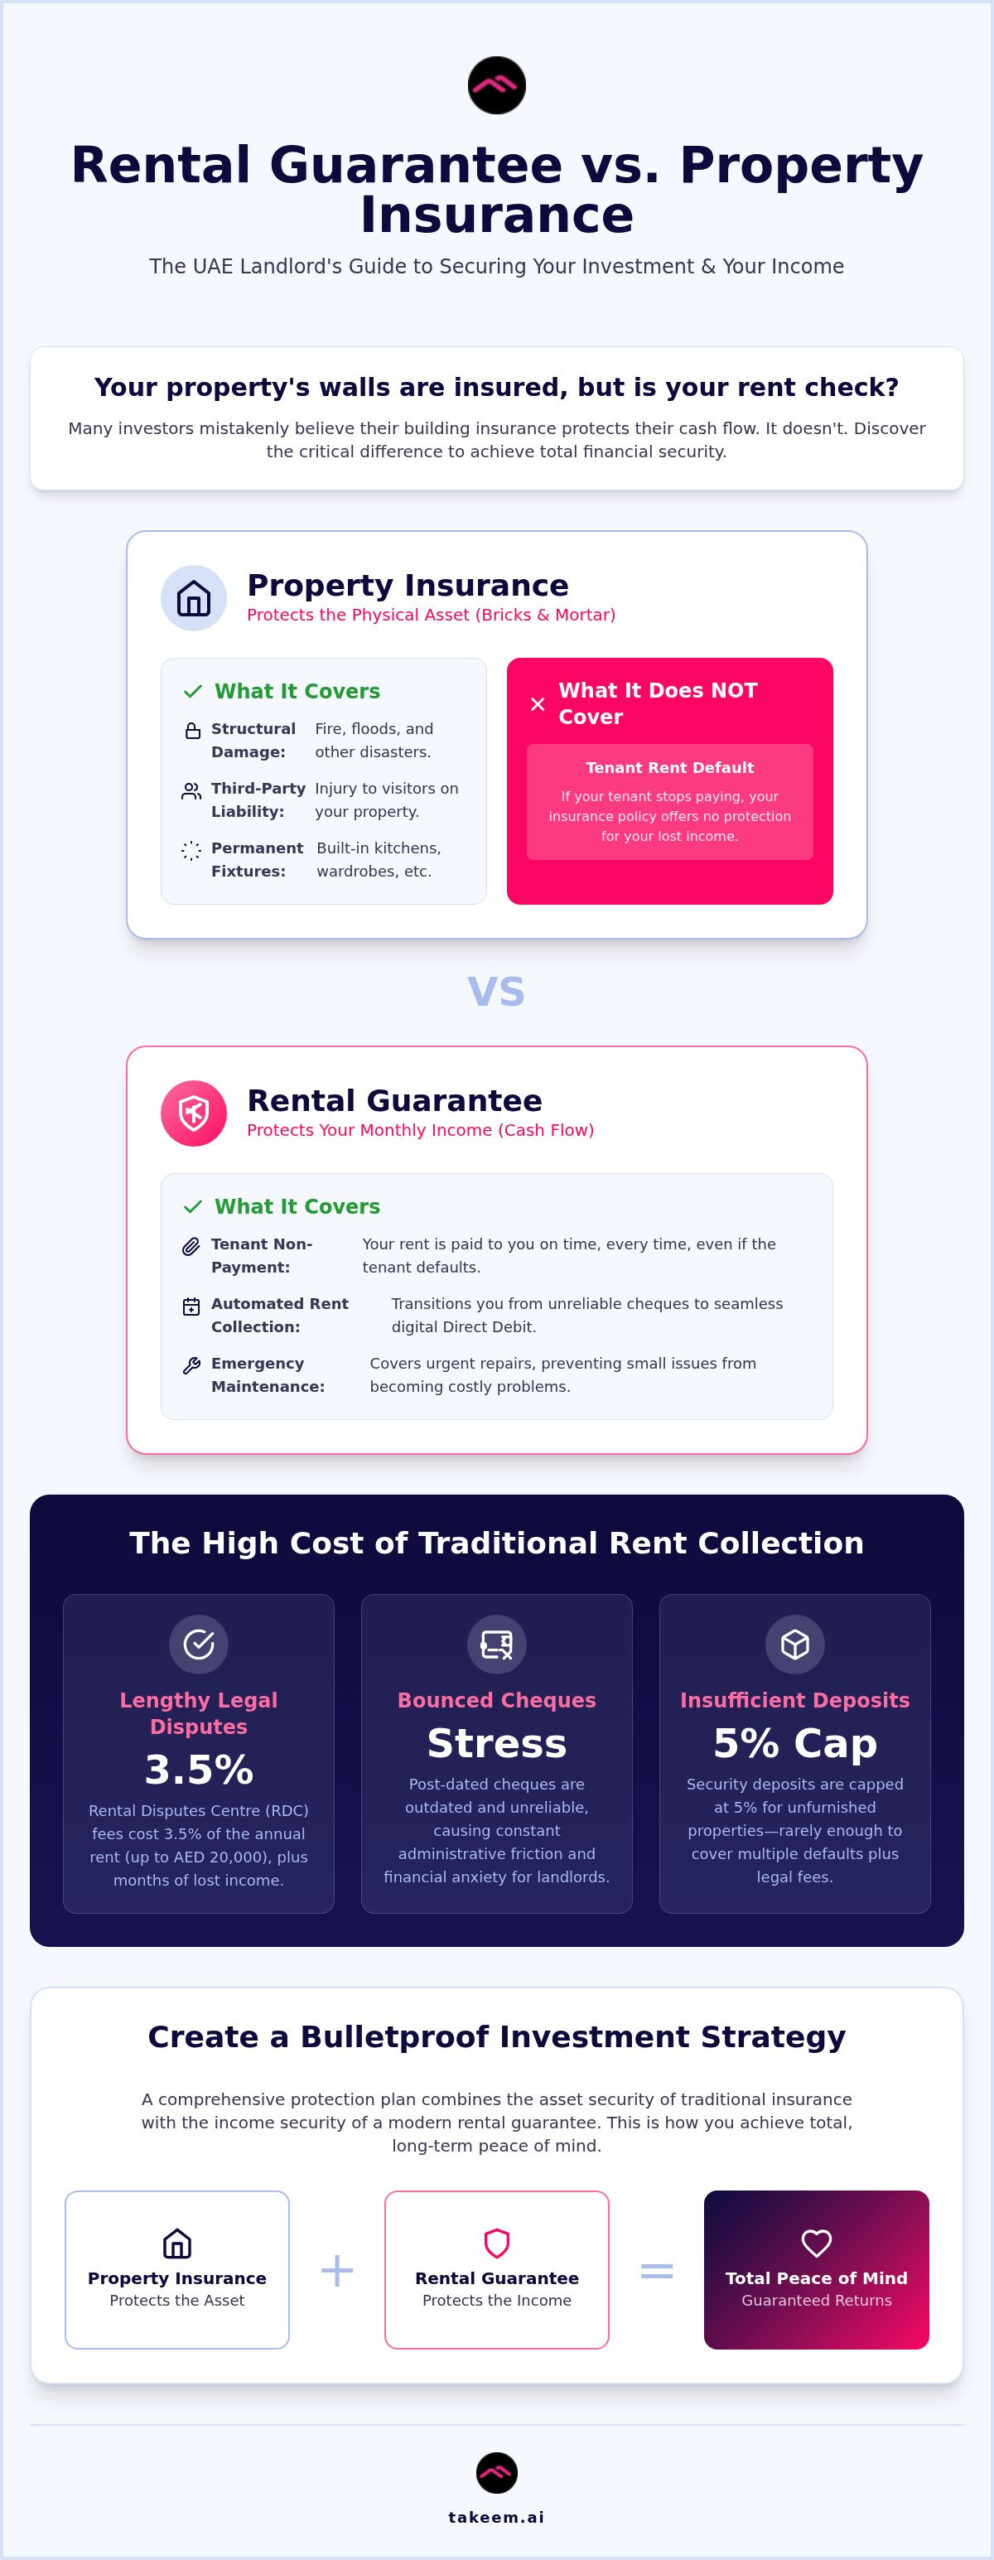
Relying on legal recourse or security deposits is often a losing game. Filing a dispute with the Rental Disputes Centre (RDC) costs 3.5% of the annual rent, with fees reaching up to AED 20,000. These costs, combined with months of lost income, create a “liquidity trap” for the owner. Security deposits, capped at 5% for unfurnished properties, are rarely enough to cover multiple months of default plus legal fees. When comparing a rental guarantee vs property insurance UAE, it’s clear that traditional insurance won’t pay your mortgage if the tenant stops paying. Proactive guarantees bridge this gap, ensuring that your investment remains a source of income, not a liability.
Property Insurance: Safeguarding the Physical Asset
Property insurance is the bedrock of risk management for any real estate owner. It’s not just a strategic choice; for investors with mortgages, it’s a mandatory requirement. This coverage protects the physical shell of your investment, acting as a shield against the catastrophic. Fire, floods, and structural failures fall under this umbrella. The World Bank’s assessment of UAE property registration highlights the efficiency and stability of the local market, but even the most secure property requires protection from physical damage. When weighing the rental guarantee vs property insurance UAE debate, it’s essential to remember that insurance looks at the bricks, while guarantees look at the bank account.
What Standard Home Insurance Covers (and What it Doesn’t)
Standard policies focus on the tangible. They typically cover structural integrity, including walls, roofs, and foundations. They also extend to permanent fixtures like built-in wardrobes and kitchen units. A critical component is third-party liability, which provides coverage if a visitor or neighbor is injured due to a fault in your property. However, it’s vital to distinguish between ‘Homeowner Insurance’ and ‘Landlord Insurance’. If you’re renting out the unit, a standard homeowner policy might be voided. The risk profile of a tenant is different from an owner-occupier, so you need a policy specifically designed for landlords to maintain valid coverage.
Insurance does not cover the intentional financial default of a tenant. If a tenant decides to stop paying rent despite the property being in perfect condition, your insurance provider will not reimburse those losses. It’s a protection for the asset, not the business operation of being a landlord.
The Reality of Insurance Payouts for Rent Default
Many landlords are surprised to find that ‘Loss of Rent’ clauses in standard insurance policies are highly restrictive. These clauses typically only activate if the property becomes uninhabitable due to a covered physical event, such as a fire or major leak. If your tenant simply disappears or stops paying while the property remains functional, insurance won’t step in. This is a primary reason why the rental guarantee vs property insurance UAE distinction is so critical for cash flow management.
- Physical Trigger: Payouts require structural damage first.
- High Deductibles: You often pay a significant portion of the claim yourself.
- Claims Latency: Traditional insurance claims can take weeks or months to process.
To bridge the gap between physical protection and financial certainty, you might consider a comprehensive rental guarantee that picks up where your insurance leaves off, ensuring your yield is never at the mercy of tenant behavior.
Rental Guarantees: Protecting Your Monthly Yield
A rental guarantee represents the next evolution in property technology. Unlike traditional insurance, which acts as a reactive safety net, a modern rental guarantee is a proactive financial buffer. It ensures that your monthly yield remains stable regardless of whether a tenant pays on time. While there’s much discussion regarding the rental guarantee vs property insurance UAE landscape, the core difference lies in the guarantor’s role. In this model, a fintech platform steps in as a reliable facilitator, ensuring 100% payment occupancy for your portfolio. This isn’t just a service; it’s a digital shield for your cash flow.
This model is rapidly becoming the standard for sophisticated investors across the UAE. It removes the friction of property management by providing a guaranteed income stream. You no longer need to worry about the specific date a tenant transfers funds. Instead, you receive your rent like clockwork, allowing you to meet your own financial obligations with total confidence. Understanding the nuances of property insurance for rental properties in the UAE is vital for asset safety, but only a guarantee secures the operational liquidity of your investment.
The Mechanics of a Rental Guarantee Service
The process starts with a seamless Direct Debit setup. This replaces the administrative burden of handling physical cheques or manual transfers. Once the system is live, the payout process becomes automated. If a tenant is late or a payment fails, the guarantee triggers an automated payout to the landlord. You move from the stress of chasing payments to the simplicity of receiving digital reports. It’s a shift toward a more institutionalized way of managing private rental property, where technology handles the risk and you enjoy the returns.
Integrated Maintenance: Preserving Value Beyond the Rent
Emergency property maintenance is often the missing piece in a landlord’s protection strategy. A leaking pipe or a broken cooling system can quickly escalate into a legal dispute or a tenant withholding rent. By integrating emergency maintenance into the rental guarantee, you create a comprehensive financial shield. Quick repairs prevent minor issues from turning into major capital expenditures that drain your profits. This synergy ensures that the rental guarantee vs property insurance UAE choice isn’t just about money, but about the total health of your asset.
- Immediate Response: Repairs are handled before they impact the tenant’s willingness to pay.
- Value Preservation: Rapid intervention ensures the long-term appreciation of the physical asset.
- Synergy: Maintenance coverage and income security work together to eliminate the most common causes of rental default.
When you evaluate your protection options, consider that insurance covers the disaster, but a guarantee manages the day-to-day stability of your yield. It’s the difference between being covered for a fire and being certain that your mortgage is paid every single month.
Side-by-Side Comparison: Coverage, Cost, and Claims
Choosing the right protection requires a clear understanding of what triggers a payout. In the rental guarantee vs property insurance UAE comparison, the primary difference lies in the nature of the risk. Property insurance triggers during physical crises like fire, flood, or structural failure. It protects your capital asset from becoming a total loss. Conversely, a rental guarantee triggers during financial friction, such as a tenant’s non-payment or a late transfer. While insurance keeps the building standing, the guarantee keeps the investment performing.
The cost structures also reflect these different goals. Annual insurance premiums are typically fixed costs based on the property’s reconstruction value. They’re a necessary expense for long-term safety. Rental guarantees usually operate on service-based fees that scale with the rental value. This isn’t just a cost; it’s an investment in operational efficiency. By shifting from DIY collection to managed digital collection, you replace the administrative burden of chasing payments with a streamlined, automated system.
Payout Speed: Insurance Claims vs. Guaranteed Income
Liquidity is the lifeblood of any property portfolio. Traditional insurance claims often involve a 30 to 90 day cycle for assessment and payout. This delay can be devastating if you’re relying on that income to cover mortgage installments or service charges. A rental guarantee operates on a scheduled day reliability. Because the system is built on digital Direct Debit, the payout is automated. You receive your rent on the expected date even if the tenant’s payment is delayed, effectively removing the stress of missed financial obligations.
Liability vs. Liquidity: Choosing the Right Shield
The most successful investors don’t choose one over the other. They adopt a hybrid approach. Liability protection via insurance is a baseline requirement, but liquidity protection via a guarantee is what allows a portfolio to scale. As your holdings grow, the complexity of managing multiple tenants increases. Mapping your protection types to different tenant profiles ensures that every unit remains profitable. For example, high-turnover units benefit significantly from the automated maintenance and payment security of a guarantee.
To see how this modern protection model fits your specific portfolio, you can explore the Landlord Rental Guarantee and secure your monthly income today. This dual-layer strategy ensures that your investment is protected from both physical damage and financial default, providing the total peace of mind every landlord deserves.
Takeem: The Modern Landlord’s Comprehensive Security Suite
Takeem provides a national solution for UAE landlords who want to move beyond the limitations of traditional protection. While previous sections have outlined the rental guarantee vs property insurance UAE debate, Takeem represents the practical application of these concepts into a single, streamlined workflow. We serve as a digital shield, combining financial security with operational excellence. By integrating modern proptech with the reliability of institutional finance, we ensure that your monthly income is never left to chance. As of 2026, Takeem has already onboarded over 95,000 units, representing more than AED 9 billion in annual rental value across the UAE.
We bridge the gap between traditional banking and modern property technology. Our platform acts as a sophisticated facilitator, allowing you to focus on growth while we handle the risk. This institutional-grade security is no longer reserved for large corporations; it’s now accessible to every individual investor seeking peace of mind.
Replacing Cheques with Direct Debit
The transition to digital rent collection is a fundamental shift in the UAE market. Takeem facilitates a step-by-step move from manual, cheque-based systems to automated Direct Debit. This doesn’t just benefit the landlord. It enhances tenant relationships by offering the flexibility of monthly payments, which reduces the financial strain on the renter and lowers the probability of default. It effectively removes the friction of “bounced cheque” stress and administrative follow-ups. For a deeper look at this transition, read our guide on Modernizing UAE Rentals: A Landlord’s Guide to Rental Guarantees and Direct Debit.
Total Portfolio Protection for Investors
Managing risk across a diverse portfolio requires more than just insurance. It requires visibility and control. Takeem offers a single dashboard where investors can monitor multiple units and track guaranteed payments in real-time. This level of oversight is paired with emergency property maintenance, which acts as a critical component of yield optimization. By addressing repairs immediately, you prevent small issues from impacting your long-term returns. This integrated approach is essential for Optimising Property Portfolio Rental Income in the UAE: The 2026 Investor’s Guide.
We also empower real estate agents to provide superior security to their clients. Through our commission-based partnership model, agents can offer the Landlord Rental Guarantee as a value-added service. This builds trust and professional authority, positioning the agent as a tech-savvy guide in a competitive market. Takeem is the comprehensive suite that turns property investment into a truly passive, risk-free enterprise.
Securing the Future of Your Property Investment
The choice between a rental guarantee vs property insurance UAE is not a matter of selecting one over the other. It’s about building a comprehensive defense that protects both your physical asset and your financial liquidity. While insurance manages the risk of structural damage, a rental guarantee ensures that your investment continues to perform regardless of market volatility or tenant behavior. You’ve seen how modernizing your approach through digital Direct Debit collection eliminates the friction of traditional cheques and provides a steady, predictable income stream.
By integrating emergency maintenance into this framework, you preserve the long-term value of your units while enjoying guaranteed monthly cash flow. This proactive strategy allows you to scale your portfolio with confidence, knowing that every unit is shielded by institutional-grade technology. It’s time to stop chasing payments and start focusing on your growth.
Secure your rental income with Takeem’s guarantee today and experience the peace of mind that comes with total protection. Your investment deserves a modern shield.
Frequently Asked Questions
Is a rental guarantee the same as landlord insurance?
No, they’re distinct protection models. Landlord insurance typically focuses on the physical structure and third-party liability. A rental guarantee is a fintech-driven solution that secures your actual income. When evaluating a rental guarantee vs property insurance UAE, think of insurance as protecting the bricks and mortar, while the guarantee protects the monthly performance of your cash flow. One is for disasters; the other is for financial reliability.
Does property insurance cover a tenant not paying rent in the UAE?
Standard property insurance in the UAE rarely covers simple rent default. Most policies only offer “loss of rent” coverage if the building is physically damaged by a covered event, like a fire, making it uninhabitable. If a tenant stops paying but the property is fine, insurance won’t help. This is why landlords use guarantees to bridge the gap between physical safety and financial liquidity.
How does Takeem’s rental guarantee work with Direct Debit?
Takeem integrates Direct Debit to replace the administrative burden of post-dated cheques. The system automatically pulls rent from the tenant’s account on a monthly basis. If the tenant has insufficient funds, the guarantee service ensures the landlord still receives the scheduled payment. It transforms the collection process into a digital, hands-off experience that prioritizes the landlord’s cash flow stability without the need for manual follow-ups.
Is emergency maintenance included in a standard UAE property insurance policy?
Standard policies usually exclude minor emergency maintenance. They’re designed for significant structural losses rather than a leaking pipe or a cooling system failure. Takeem includes emergency property maintenance as a core part of its rental guarantee. This ensures that urgent issues are resolved quickly, protecting the asset’s value and preventing maintenance disputes from leading to tenant payment defaults or long-term structural damage.
Can I have both property insurance and a rental guarantee?
Yes, and combining both is the most effective way to achieve total protection. Insurance provides the mandatory structural coverage often required by lenders, while a guarantee provides the income security needed for mortgage payments. Using them together creates a comprehensive shield that covers every possible risk, from a natural disaster to a tenant’s sudden change in financial circumstances, ensuring your investment remains profitable.
What happens if a tenant defaults while I have a Takeem guarantee?
If a tenant defaults, your income remains uninterrupted. Takeem’s system detects the failed Direct Debit and triggers the guarantee payout to your account on the scheduled day. The platform then manages the recovery process and administrative hurdles. You don’t have to deal with the stress of legal filings or chasing payments, as your yield is already secured by the digital guarantee framework.
Is Direct Debit legally recognized for rent collection in the UAE?
Direct Debit is fully recognized and increasingly encouraged as a secure method for rent collection across the UAE. It provides a transparent, digital trail that reduces the risks associated with physical cheques. Regulatory shifts are moving toward these automated systems because they offer better protection for both parties. It’s a modernized approach that aligns with the country’s push for a digital-first economy and reduces payment friction.
How much does a rental guarantee cost compared to traditional insurance?
Insurance premiums are typically based on the property’s reconstruction cost and are paid annually. Rental guarantee fees are service-based and tied to the rental value of the property. While the structures differ, the guarantee provides a broader operational benefit by automating collection and including maintenance. Both are essential investments for any serious landlord looking to minimize risk and maximize the performance of their national property portfolio.